The Role of Insurance in Financial Planning

By Trilogy Financial
March 28, 2023
Share on:

Financial planning involves thoughtfully outlining objectives and setting goals in your Life Plan. With anything, the possibility of running into obstacles, options, and challenges throughout your financial journey is unavoidable. That’s why it is important to implement some sort of checks and balances to mitigate these challenges. Insurance is one of the best ways to account for unforeseen conditions and events in your financial plan. The thought of utilizing insurance can be daunting. It makes the possibility of losing your car or home due to an accident, flood, or fire a reality. That’s exactly why we create a financial plan – to be prepared for the unexpected. Our team is committed to coaching you through the process, so that you can make an informed and confident decision. There are various types of insurance services available that your Trilogy Financial advisor can help you navigate so you can handle the many uncertainties that life throws your way.

Read on to discover these insurance services.

Insurance Services Provided by Trilogy Financial

Every Trilogy Financial Advisor is committed to helping you build the legacy you have always desired to leave through the following services:

Term Insurance

A term insurance policy is the most common form of temporary life insurance. The term usually lasts for a specific “term” of years. Term insurance is also a form of insurance that is rented. Meaning, you pay a monthly premium for the insurance, but it expires after the allotted time frame. The duration can range from five to thirty years.

Term insurance protects liabilities that will cease to exist after a specific period, such as providing extra cashflow for raising children. It is a simple life insurance plan that protects against the possibility of an untimely death. A death benefit is granted if the insured passes away during the policy's stated tenure.

Because death is unpredictable, term insurance plans are essential. The family may experience a significant financial loss if the family's primary provider passes away. A term plan covers the loss. It benefits the family, allowing them to cover lifestyle costs and continue to address their financial objectives.

Permanent Insurance

Permanent insurance can be considered “owning” insurance coverage. Like term insurance, you pay a monthly premium; however, in permanent insurance, the range is continuous and does not end within a time frame.

For instance, even after your children have moved out and your liabilities have diminished, you may continue to carry some form of insurance to cover your loved ones and compensate for your end-of-life needs.

Permanent insurance premiums are more significant than term insurance premiums because, unlike term insurance, the insurance company may never have to pay out the policy. Permanent insurance can be used as an income and an insurance tool. Both a death benefit and a cash value factor are included. You can access the money as the value increases by taking out a loan or a withdrawal, and you can terminate the insurance by withdrawing the cash value.

Long-Term Care Planning

Long-term care planning, at its foundation, entails ensuring that you or a loved one's needs are adequately met when they can no longer care for themselves. Therefore, as you age, having a practical plan becomes more and more crucial. While many maintain their independence well into their senior years, it never hurts to plan.

Any long-term financial plan should consider long-term care costs, especially if you are in your 50s or older. You are unlikely to qualify for long-term care insurance if you already have a disabling condition. Most over 75 applicants will not be accepted by long-term care insurance providers. Most persons who purchase long-term care insurance do so between 50 and 60.

Risk Management

Risk management entails recognizing, assessing and managing risk. A well-executed risk management program is built on a foundation of standardized risk assessments to assist businesses in prioritizing their risk based on its potential impact. This procedure will inevitably reveal hazards affecting the company's fundamental competencies.

As financial Advisors, it is a part of our job to help you navigate your financial well-being, which includes helping you mitigating certain risks. Identifying your risk factors is your first defense, followed by avoiding or limiting risks to your income and survivors. Insurance is your quality line of defense.

Importance of Insurance in Financial Planning

Here are some factors that make insurance an essential aspect of your Life Plan:

  • Financial assurance: You feel safe knowing that the insurance policy will cover the damages in the event of an emergency.
  • Tax advantages: Insurance lowers your taxable income and provides financial benefits.1
  • Risk protection: Insurance prepares you to deal with any financial loss you might suffer in the event of an unplanned circumstance.
  • Meeting your prerequisites: Several insurance policies are available to cover the various risks you can encounter.
  • Peace of mind: Insurance plans assure you that your funds will not be compromised in the event of an emergency.

*This information is not intended as authoritative guidance or tax advice.  You should consult with your tax advisor for guidance on your specific situation.

Why Choose Trilogy Financial

Your financial plan should be strategically in line with your insurance. Our Trilogy Financial Advisors use a comprehensive strategy to offer insurance policies tailored to your specific needs and Life Plan. We understand the risks you face and how to help improve your financial life. Our Advisors will work with you to develop a deeper understanding of your alternatives, pinpoint practical needs and make plans for the care you and your family deserve.

To help you build the life you’ve dreamed, we collaborate with the most reliable insurance firms with a track record of being financial secure and capable of paying claims.

Get Started with a Financial Advisor Today

Everyone has a distinct level of risk, and before purchasing insurance, it is critical to identify risks and establish how to limit the likelihood of them occurring. We understand that everyone has a varying level of comfort and experience in navigating finances and Life Plans. That’s why our Advisors are committed to being both a partner and coach to support you as much or as little as you need, so you can make the best decisions for you and your family.

At Trilogy Financial, our Advisors will guide you through your daily financial decisions to keep you on track and set you up for your real-life goals. If you have any questions concerning insurance or any other element of your financial life, get in touch or visit our website today to book a meeting with an advisor
 

happily discussing insurance plan after meeting with financial advisor


You may also like:

By Trilogy Financial
February 20, 2024

Introduction:


Selecting a qualified financial planner is crucial for securing a robust financial future. A proficient planner, like those at Trilogy Financial, can create a financial plan tailored to your unique needs to help you reach your goals.  Yet, a staggering 74% of Americans engage in financial planning without professional guidance, revealing a potential gap in making informed choices​2​.


Advisor meeting clients.


Mistake 1: Overlooking Qualifications


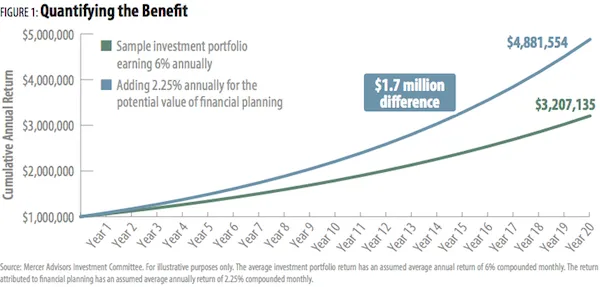
Chart quantifying the benefit of a financial planner.


  • Stat: Smart financial planning can yield 1.5% more in annual average returns, underlining the importance of qualified guidance​3​.
  • Tip: When choosing an advisor ensure  your planner holds pertinent certifications and showcases a robust track record of expertise.
  1. What are pertinent certifications for a financial planner?Pertinent certifications include the Certified Financial Planner (CFP), Chartered Financial Analyst (CFA), and Certified Public Accountant (CPA) designations. These certifications indicate a high level of expertise and adherence to industry standards.
  2. How can I verify a financial planner's certifications?You can verify a planner's certifications by checking the databases of certifying bodies like the CFP Board or the CFA Institute. Additionally, you can ask the planner for proof of certification.
  3. What constitutes a robust track record of expertise?A strong track record includes many years of experience, successful financial planning, happy clients, and industry recognition or awards.
  4. How can I assess a financial planner’s track record?You can assess a planner’s track record by reviewing client testimonials, checking for any industry awards or recognitions, and asking for references. Additionally, verifying their work history and experience in the field can provide insights into their expertise.


Mistake 2: Neglecting Fee Structures


  • Stat: According to a 2019 Financial Trust Survey, “Nearly half of Americans (48%) incorrectly believe all financial advisers have a legal obligation to act in clients’ best interests.”4.
  • Tip: Understand the fee structures and ensure transparency in your financial engagements if you chose to work with a financial advisor.
  1. What are common fee structures in financial planning?Common fee structures include fee-only (fixed, hourly, or percentage of assets managed), commission-based, and fee-based (a combination of fees and commissions).
  2. How can I ensure transparency in fee structures?Ask your financial planner for a clear, written explanation of all fees and charges, including any potential third-party fees, before engaging their services.
  3. What is the difference between fee-only and fee-based financial planners?Fee-only planners charge a flat fee, hourly rate, or percentage of assets managed, and do not receive commissions from selling financial products. Fee-based planners, on the other hand, may charge fees and also receive commissions, which could potentially lead to conflicts of interest.
  4. How do commissions affect the advice I receive?Commissions could potentially create a conflict of interest if a financial planner is incentivized to recommend certain products that earn them commissions, rather than what's in your best interest.


Mistake 3: Disregarding a Personalized Approach


Advisor providing a personalized approach to financial planning


  • Stat:  A Bankrate 2019 survey shows that 44% of individuals with a personal finance plan save more for retirement and 43% save 50% more per month.​5​
  • Tip: When hiring a financial advisor opt for financial planners like those at Trilogy Financial, who prioritize a personalized approach to meet your unique financial objectives​​.
  1. What does a personalized approach in financial planning entail?A personalized approach means that the financial planner takes the time to understand your individual financial circumstances, goals, risk tolerance, and future aspirations to craft a strategy tailored to meet your unique needs.
  2. Why is a personalized approach important in financial planning?A personalized approach ensures that your financial plan is aligned with your goals and circumstances, which can lead to better financial outcomes and satisfaction over time.
  3. What are some examples of unique financial objectives that would benefit from a personalized approach?Unique financial objectives could include planning for early retirement, saving for a child's education, managing a large inheritance, or preparing for a significant life change like marriage or starting a business.
  4. How does a personalized approach compare to a one-size-fits-all approach in financial planning?A personalized approach provides tailored advice and strategies based on your individual circumstances, which can lead to more effective financial planning and better outcomes compared to a one-size-fits-all approach that may not align with your personal goals and risk tolerance.


Mistake 4: Ignoring a Comprehensive Service Offering


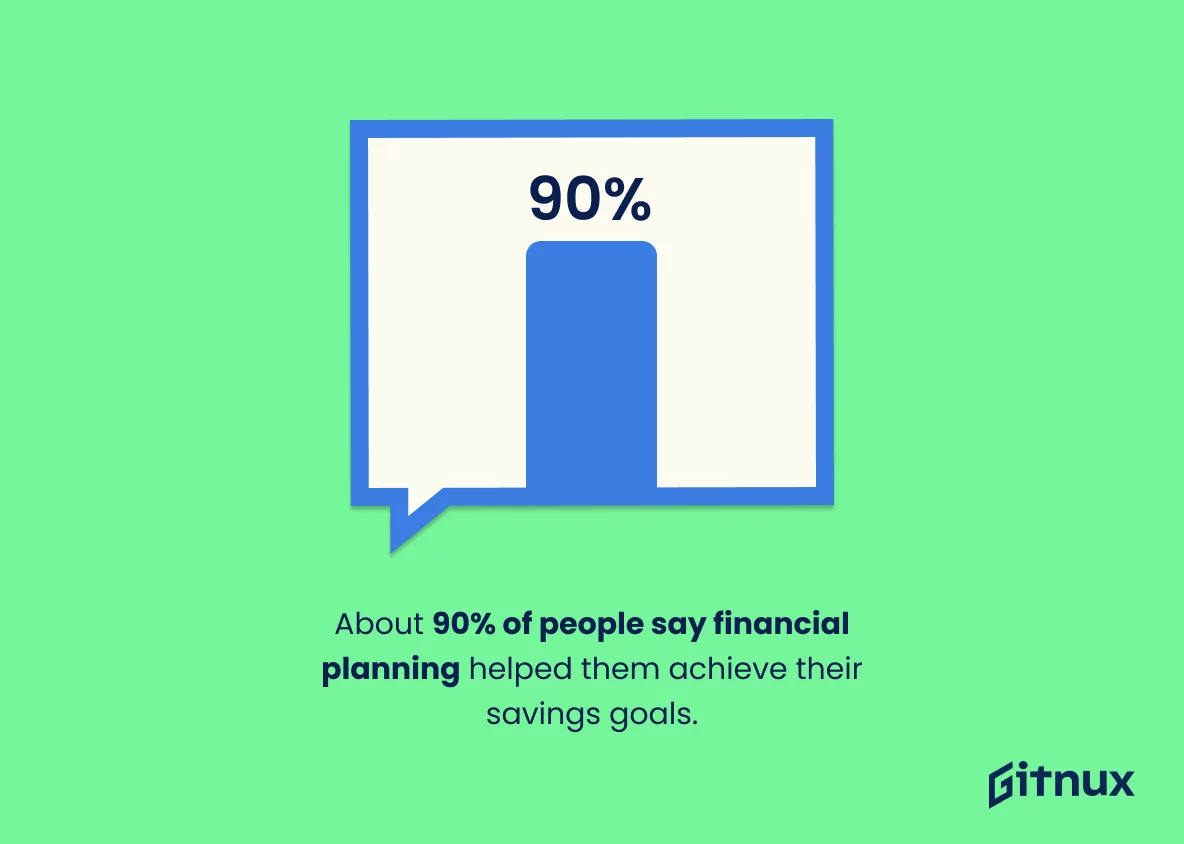
Chart showing 90% of people say financial planning helped them achieve their saving goals.


  • Stat: A whopping 90% of individuals achieved their savings goals owing to comprehensive personal finance plans, emphasizing the necessity of a holistic service offering​ 6​.
  • Tip: Choose a planner offering a spectrum of services including retirement planning, estate planning, and risk management.
  1. Why is it important for a financial planner to offer a variety of services?A variety of services allows for a holistic approach to financial management, ensuring that all aspects of your financial life are considered and managed in a coordinated manner. This might include mutual funds, tax planning, and more.
  2. What is retirement planning, and why is it crucial?Retirement planning involves preparing for life after you stop working, which includes saving, investing, and making other financial arrangements to ensure a comfortable living post-retirement.
  3. What does estate planning entail?Estate planning involves the management and disposal of an individual's estate during their life and at and after death, while minimizing gift, estate, generation skipping transfer, and income tax.
  4. What is risk management in the context of financial planning?Risk management in financial planning refers to the identification, assessment, and strategizing to mitigate or manage financial risks that could negatively impact your financial situation.


Mistake 5: Underestimating Continuous Communication


  • Stat: Clients report higher satisfaction levels with higher frequencies of investment-related educational communications and scheduled meetings, underscoring the importance of continuous communication​ 7​.
  • Tip: Ensure your financial planner maintains open channels of communication, keeping you informed and engaged throughout your financial journey.
  1. How can I ensure that my financial planner maintains open channels of communication?
    You can set expectations for communication upfront, such as preferred methods of communication and frequency of updates. It's also helpful to choose a planner who is responsive and willing to engage in regular discussions about your financial plan.
  2. Why is communication important in financial planning?
    Communication is crucial to ensure that you and your financial planner are on the same page regarding your financial goals, risk tolerance, and any changes in your financial circumstances. It also helps in building trust and understanding throughout the financial planning process.
  3. What are some red flags regarding communication with a financial planner?
    Red flags could include lack of responsiveness, unwillingness to answer your questions, failure to provide clear explanations, or not initiating regular reviews and updates as agreed upon.
  4. How can effective communication with a financial planner impact my financial journey?
    Effective communication can lead to better understanding, trust, and alignment between you and your planner, which in turn can result in a more effective financial plan and a more satisfying financial journey.


Conclusion:


Avoiding these common pitfalls when choosing a financial planner can significantly steer your financial voyage towards success. Engaging with a reputable firm like Trilogy Financial not only helps sidestep these mistakes but also ensures a tailored, client-centric approach delivered by qualified professionals, fostering transparent communication throughout your financial journey​1​.


By
Mike Loo, MBA
November 2, 2018

In 2015, Americans spent $225 billion on long-term care. That’s 7 ½ times what was spent 15 years prior, in 2000. With the great advances we have made in medicine and medical technology, people are living longer. The downside to that is that it means people are more likely to need care and need it longer. In fact, over half of people turning 65 will need long-term care at some point in their lives.(1)

Types Of Long-Term Care

When you think of long-term care, skilled nursing facilities are probably what comes to mind. However, that is actually the last step in the long-term care journey. Most long-term care is not medical; it is simply assistance with basic activities of daily living like bathing, dressing, eating, and going to the bathroom.

Even without serious medical problems, most people become less and less capable of taking care of themselves as they age. Traditionally, people would turn to family for help with such things. However, in our modern era where families live far apart and adult children are already overburdened with careers and children, more and more people have to pay for long-term care services.

The most basic, and least expensive, form of care is homemaker services. Homemaker services do not involve anything medical, but rather things like meal preparation, cleaning, and running errands. The next step up, which does have a medical component, would be a home health aide.

Once basic in-home assistance is not enough, specialized facilities are needed. Care outside of the home can be in the form of adult day healthcare, assisted living facilities, and nursing homes.

Costs Of Long-Term Care(2)

Costs vary depending on the type of care needed and the part of the country in which you live. On an annual basis, the national average goes from just under $48,000 for homemaker services to over $97,000 for a private room in a nursing home, and that number is growing about 3-4% a year.

Things change drastically when you look at specific locations. In San Francisco, homemaker services are more than 150% the national average and growing twice as fast. A private room in a nursing home averages $171,185 a year. Even downgrading to a semi-private room still costs over $141,000 a year. Twenty years from now, that same semi-private room is expected to cost over a quarter of a million dollars.

As you can see, long-term care can be very expensive, especially with the rise of dementia, where people can live a long time while needing care. In 2018, the estimated lifetime cost of care for someone with dementia is $341,840,(3) and it’s probably much higher in a state like California.

Ways Of Paying For Long-Term Care

Because of the high cost, it is important to plan ahead for long-term care. There are a number of ways to pay for care, each with its advantages and disadvantages.

Medicaid

The vast majority of Americans turn to Medicaid for their long-term care expenses. However, it’s not because it’s a great option. Rather, it’s their only option. In order to qualify for Medicaid, you have to have a low income and low assets, so it’s not really something people plan for intentionally.

Self-Insure

On the opposite end of the spectrum from the people that can qualify for Medicaid are those who have amassed enough wealth to self-insure. If you have $50 million in assets, you can afford to pay $170,000 a year for a nursing home and it won’t have a significant impact on your finances.

The danger is that sometimes people take too great a risk thinking they can self-insure. Often, care is needed later in retirement when savings have already been spent down significantly. Having $500,000 in the bank may seem like a lot of money, but long-term care expenses can eat through it very quickly. Unfortunately, it’s not uncommon for a couple to spend all of their savings on the husband’s care only to leave the wife destitute at his passing.

Life Insurance With A Long-Term Care Rider

One option for those that find themselves in between broke and very wealthy is adding a long-term care rider to their life insurance. If you have, or are planning on purchasing, permanent life insurance, your policy may allow you to add a rider that would help pay for your long-term care costs. Using the long-term care option will often lower your death benefit, but many people appreciate knowing they will receive a benefit even if they never need long-term care.

Premium Paying Long-Term Care Insurance

Another option is buying pure long-term care insurance. Like with most kinds of insurance, you pay a regular premium in exchange for receiving a benefit when you need long-term care. One downside to this for many people is that you will only receive a benefit if you end up needing long-term care. As with car insurance where you have to get into an accident in order to get money out of it, if you never need care, you never see your money again.

Asset-Based Long-Term Care Insurance

The final option has been the fastest growing long-term care option over the last decade.(4) It is a combination of long-term care insurance and single premium life insurance, commonly called asset-based insurance.

The way it works is that you pay a large amount up front and then low annual premiums. You have several times your initial deposit available tax-free for long-term care needs. If you never use it or cancel your plan, you usually get your deposit back plus interest. Some plans even include tax-free death benefits.

Choosing A Long-Term Care Option

Looking at the statistics, you can tell that planning for long-term care is an important thing to do. Failing to do so can be a costly mistake. Because the multitude of options available can be complex and confusing, it’s important to work with an experienced financial professional.

An experienced advisor can explain all of your options to you, help you consider the pros and cons of each, and decide which is the best solution for your particular situation. If you want that kind of help choosing a long-term care option, call my office at (949) 221-8105 x 2128, or email me at michael.loo@lpl.com to set up a no-strings-attached meeting.

(1) https://www.morningstar.com/articles/879494/75-mustknow-statistics-about-longterm-care-2018-ed.html

(2) https://www.genworth.com/aging-and-you/finances/cost-of-care.html

(3) https://www.morningstar.com/articles/879494/75-mustknow-statistics-about-longterm-care-2018-ed.html

(4) https://www.525longtermcare.com/asset-based-ltci/

Get Started on Your Financial Life Plan Today