|
|
Have you ever envisioned a life where the chains of daily grind are broken well before the conventional retirement age, paving the way for a life of financial freedom and leisure? Embracing financial discipline and frugality can pave the way to a comfortable early retirement, answering the pressing question: Can meticulous financial planning and a frugal lifestyle significantly hasten your journey to early retirement?
Financial planning goes beyond merely saving a portion of your income; it's about understanding and rectifying financial bad habits that may impede your journey towards financial stability. Everyday financial misbehaviors such as impulsive spending, credit card debt, and the lack of a structured financial plan for emergencies often go unnoticed but have a long-term detrimental impact on financial health. Addressing these personal finance habits is the first step in financial planning.
Frugality is about making informed and restrained financial decisions to save money. A frugal lifestyle encourages avoiding unnecessary expenses and finding value in what you spend.
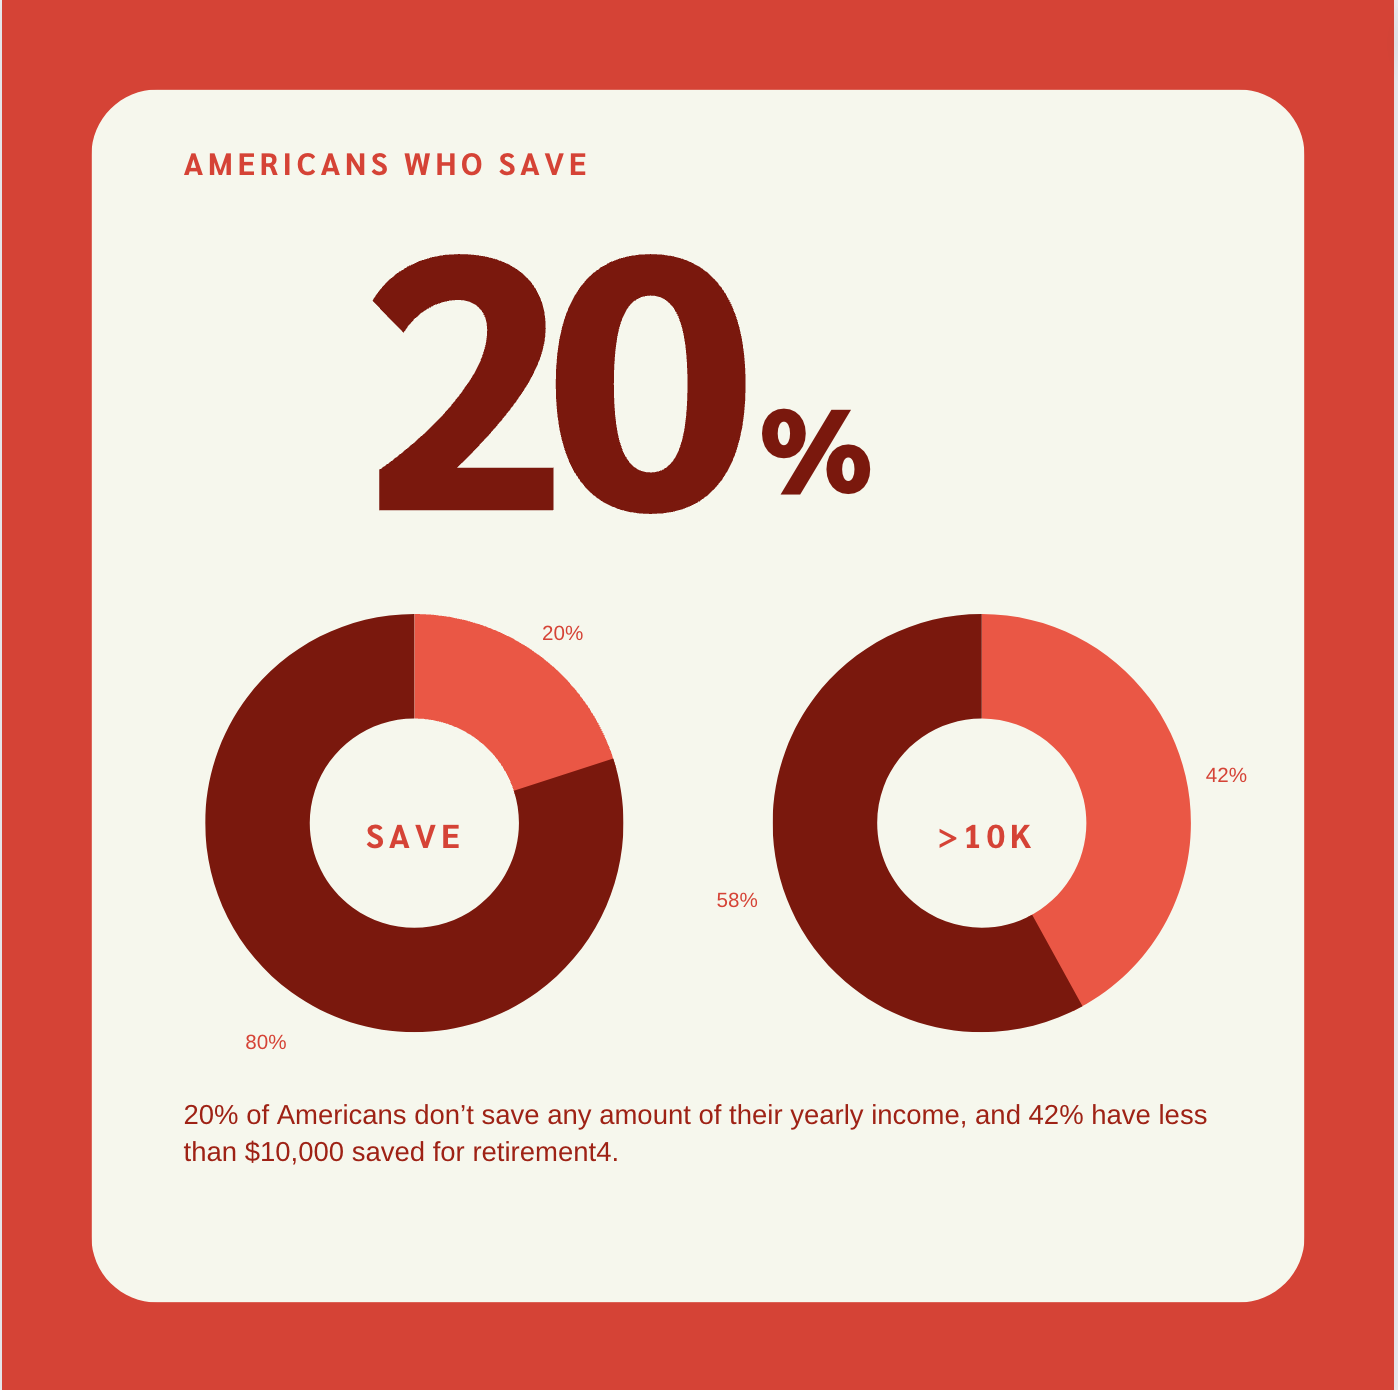
Did you know 20% of Americans don’t save any amount of their yearly income, and 42% have less than $10,000 saved for retirement4.
There are myriad tools and resources available to aid in your financial planning journey. Budgeting apps, financial advisors, and online courses are excellent resources. Trilogy Financial, for instance, offers a Decision Coach program designed to provide additional accountability and coaching to individuals seeking financial guidance.
Easily Meet with a Certified Financial Planner.
The quest for early retirement often begins with a thorough re-evaluation of one's financial plan, identifying areas of improvement, and capitalizing on unforeseen savings opportunities. The year 2020 saw many Americans saving more, with an average of 10% more money saved compared to 2019, mainly due to lifestyle changes induced by the pandemic. Some redirected these savings towards home improvements, while others saw it as a stepping stone towards drafting a solid financial plan aimed at debt reduction, college planning, or accelerating the journey to financial independence.
Various individuals and communities dedicated to frugal living and meticulous financial planning have emerged over the years, showcasing diverse pathways to early retirement. Here are a few noteworthy examples:
These cases highlight the transformative impact of frugal living and prudent financial planning to achieve early retirement dreams. They speak to the importance of continuous financial plan evaluation, adapting to changing circumstances, and leveraging savings opportunities to expedite the journey to financial independence and early retirement.
The road to early retirement is laden with challenges, primarily stemming from our own financial bad habits. However, if we create a financial plan, adopt a frugal lifestyle, and leverage available resources, overcoming these challenges and retiring early is an achievable goal.
Preparation for retirement is extremely important, and it extends well beyond finances. In addition to knowing how you’re going to fund it, you also need to know what your time will look like when you say you’re done with being a wage earner. With this new lifestyle, you not only need to determine how to fill up the hours in the day, but you also need to determine what your new purpose is. This can be a pretty significant task, which becomes even more complicated when you add another person to the equation. That’s why you need to work on your retirement compatibility with your partner way before you stop working.
Retirement Compatibility is a tricky thing. Statistics show that half of the couples disagree on their retirement age —and a third don’t see eye-to-eye about their expected lifestyle in retirement[i]. This is troubling as there are a lot of logistics you need to determine in this new chapter of your life. Will you be retiring at the same time? Typically, only 1 in 10 couples retire together[ii]. If you and your partner are planning on retiring at different times, you may want to look into how this change affects your health insurance. You may also want to consider re-establishing household roles. Equally important, you will need to find common ground on your retirement budget as it will require commitment from both parties.
Oftentimes, the difficulties in transitioning from a wage-earner to a retiree can go beyond the logistics. Some experience a period of depression as they look for a new purpose in life. As tempting as it may be, that new purpose shouldn’t be your partner. If you don’t plan correctly, you will suffer from what I call too much togetherness. This can be a very real strain on relationships. Instead, look at your life as being divided into “You Time, Me Time, and We Time.” To aid in this transition, you may want to try winding down your career gradually in order to practice retirement. This can prove to be a benefit to both yourself as you experiment with this new stage in your life and your employer as you stay on to train and mentor your replacement.
Start working on your retirement compatibility with your partner with regular financial date nights. Start discussing how you envision that new chapter in your life. What type of lifestyle do you want to live? Will there be a lot of dinners out with friends or home-cooked meals watching your favorite television show? Will you be traveling or developing a new passion? Will you work part-time or volunteer? Communication is key. Share your plans with your partner so that the two of you stay on the same page and prevent incorrect assumptions from being made.
Retirement, a lifestyle of six Saturdays and one Sunday, can be either a wonderful time or a stressful transition, depending on your planning. Make sure you and your partner’s planning extends beyond finances to ensure a smooth and joyous new chapter in your lives.
[i] https://www.fidelity.com/bin-public/060_www_fidelity_com/documents/couples-retirement-fact-sheet.pdf
[ii] https://assets.aarp.org/rgcenter/general/retired_spouses.pdf
The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual. To determine what is appropriate for you, consult a qualified professional.