Romance Scams

By Trilogy Financial
August 1, 2023
Share on:

A romance scam, also known as an online dating scam, is when a person gets tricked into believing they’re in a romantic relationship with someone they met online, when in fact their other half is a cybercriminal using a fake identity to gain enough trust to ask — or blackmail — them for money.

Oftentimes, a romance scammer starts on dating sites or apps. But scammers have increasingly started finding targets on social media, too.

After connecting with someone through a fake profile, the scammer will strike up a conversation and start building a relationship by regularly chatting with them. Once they start to trust the romance scammer and believe they have a truthful relationship, the cybercriminal will make up a story, ask them for money, and vanish.

Types of Romance Scams

Some of the most common internet dating scams include:       

Fake Dating Sites: Scam dating sites claim to be legitimate but are actually filled with scammers or underpopulated. These websites are created to mine your information.

Photo Scams: Scammers will convince their target to send their personal information in exchange for intimate photos.

Military Romance Scams: The scammer will pose as a military member, likely deployed. They build trust by using military jargon and titles, then ask for money to cover military-related expenses, such as flights home.

Intimate Activity Scams: The scammer connects with their target on multiple social media websites. Once they become closer, the scammer convinces them to undress and then threatens them with the recordings.

Code Verification Scams: Scammers will send a fake verification code through email or text, posing to be a dating app or website. Once clicked on, it will ask for their personal information, including Social Security number and credit cards.

Inheritance Scams: Scammers will make their target believe they need to get married in order to get their inheritance. In this case, they will ask them to help pay for something like airfare.

Malware Scams: Malware is also common on dating sites. In this case, the recipient will interact with a scammer who sends them a website that looks legitimate; however, it's a page that includes malware.

Tips To Avoid Losing Money To a Romance Scam

  • Protect yourself and older loved ones by raising awareness. Although this can be an uncomfortable topic, make sure you, your family and your friends are familiar with romance scams. The more you know about these scams, the better prepared you are to prevent being a victim.
  • Check in on older loved ones. Scammers are seeking to target those living alone or grieving the loss of a spouse as they are more vulnerable.
  • Limit what you share online.Scammers can use details shared on social media and dating sites to better understand and target you.
  • Do your research.Research the individual’s photo and profile using online searches to see if the image, name or other details have been used elsewhere.
  • Go slowly and ask lots of questions.Don’t let the individual rush you to leave a dating service or social media site to communicate directly.
  • Listen to your gut.If the individual seems too good to be true, talk to someone you trust.
  • Don’t overshare personal information.Requests for inappropriate photos or financial information could later be used to extort you.
  • Be suspicious if you haven’t met in person.If the individual promises to meet in person, but consistently comes up with an excuse for cancelling, be suspicious.
  • Don’t send money.Never send money to anyone you have only communicated with online or by phone.

Think you’ve been scammed?

  1. Stop communicating with the individual immediately.
  2. Talk to someone you trust and describe what’s going on.
  3. Report the incident to local law enforcement.
  4. Submit a fraud complaint with the Federal Trade Commission.

Dating scams can have devastating consequences on individuals seeking love and companionship online. It's crucial to be aware of the red flags and take necessary precautions to protect yourself from falling victim to these fraudulent schemes. Even if it’s too late to recoup losses, details may help others from becoming a victim.
 

You may also like:

By
Rebecca DeSoto, CDFA®
March 12, 2018

Each of our lives is comprised of elements that create a story. Our financial lives are no different – the elements include our bank accounts, retirement accounts, mortgages, car loans, student loans, investment accounts, stock options at work, life insurance policies, credit cards, etc. When most people think of their financial life, they think of these elements but have trouble contextualizing them in their overall financial story. All of these elements are simply tools that either help or deter us from our goals. Before analyzing the tools, it’s important to understand why you’re using them and the goals and priorities that create the story which requires them.

One way people analyze these tools is by researching investment returns. Before delving into the world of returns, think about why you are investing in the first place. Your investments should reflect your overall financial priorities. If the risk tolerance in your investment appropriately reflects the time-frame you plan on needing the money, then worrying about investment returns day-to-day can be more of a headache than it’s worth. For example, if you are 35 years old saving for retirement at 60 – you should be aggressively invested if you’re comfortable with that. Because you have 25 years before you plan on using the money, short-term fluctuations in the market shouldn’t really concern you. In fact, if the market does go down and you are still contributing to your retirement, you are technically “buying on sale” – getting more shares for the same dollar value. Contributing to your retirement in up-and-down markets is called “dollar-cost-averaging” – meaning you average out the cost/share of an investment by contributing consistently rather than trying to time the market and invest when you are “buying low”.

There are many benchmarks in the financial industry to compare your investments to and track performance. Some examples include the S&P500 and the Dow Jones Industrial Average for large-cap stocks, the Barclays US Aggregate Bond Index for bonds, and the MSCI Index for international investments. It’s important to understand how your investments are doing in relation to the overall market – it keeps you abreast of what you are investing in and prompts questions you may not ask otherwise – such as what fees you are paying, who’s helping you decide what to invest in, and how much risk you’re taking on compared to the benchmarks you’re using as a comparison. However, the benchmark you should habitually pay more attention to than any other is your particular goal with each investment and your overall goals in terms of building wealth.

Focusing on investment returns only paints half of the picture when tracking progress because it is completely out of your control. If you can confidently say your investments are well diversified and invested according to a risk-tolerance you are comfortable with, there is a much more important benchmark to track than returns. Instead of relying on your investment vehicles to do all the heavy-lifting, you should use your investment behavior as the ultimate indicator to determine if you’re making progress or need more work. What are the financial goals you have in mind? To retire by 55? To save for a second down payment on a house? To pay off your mortgage? Help your children pay for their college tuition? Protect your investments and family in case of a long-term illness? Reduce credit cards and student loans? Build emergency savings?

When you are focused on goal-based financial planning, there are a lot of benchmarks to concern yourself with other than the hype involved in investment performance. Are you saving more this year than you were last year? Did you increase your savings rate when you received a raise? Does the money you are spending appropriately reflect the values and priorities that are most important to you? Are you using extra income to increase investments and decrease liabilities? By focusing on why you’re investing in the first place and the priorities that matter to you, it’s easier to ask the right questions and monitor progress. Once you know what you’re shooting for, a Decision Coach can help you understand the appropriate tools to get there.

The Standard & Poor’s 500 Index is a capitalization weighted index of 500 stocks designed to measure performance of the broad domestic economy through changes in the aggregate market value of 500 stocks representing all major industries.

The Dow Jones Industrial Average is comprised of 30 stocks that are major factors in their industries and widely held by individuals and institutional investors.

The Bloomberg Barclays U.S. Aggregate Bond Index is an index of the U.S. investment-grade fixed-rate bond market, including both government and corporate bonds.

The MSCI EAFE Index is a free float-adjusted market capitalization index that is designed to measure the equity market performance of developed markets, excluding the US & Canada. The MSCI EAFE Index consists of the following developed country indices: Australia, Austria, Belgium, Denmark, Finland, France, Germany, Hong Kong, Ireland, Israel, Italy, Japan, the Netherlands, New Zealand, Norway, Portugal, Singapore, Spain, Sweden, Switzerland and the UK.

Each index is an unmanaged index which cannot be invested into directly. Unmanaged index returns do not reflect fees, expenses, or sales charges. Index performance is not indicative of the performance of any investment. Past performance is no guarantee of future results.

By Trilogy Financial
February 20, 2024

Have you ever envisioned a life of Financial Freedom and Leisure?

Have you ever envisioned a life where the chains of daily grind are broken well before the conventional retirement age, paving the way for a life of financial freedom and leisure? Embracing financial discipline and frugality can pave the way to a comfortable early retirement, answering the pressing question: Can meticulous financial planning and a frugal lifestyle significantly hasten your journey to early retirement?


What Makes Financial Planning Crucial?


Financial planning goes beyond merely saving a portion of your income; it's about understanding and rectifying financial bad habits that may impede your journey towards financial stability. Everyday financial misbehaviors such as impulsive spending, credit card debt, and the lack of a structured financial plan for emergencies often go unnoticed but have a long-term detrimental impact on financial health. Addressing these personal finance habits is the first step in financial planning.


  • Why is Debt Management Essential? A key aspect of financial planning involves managing or eliminating debt, which can otherwise consume a significant portion of your income in the form of interest payments.
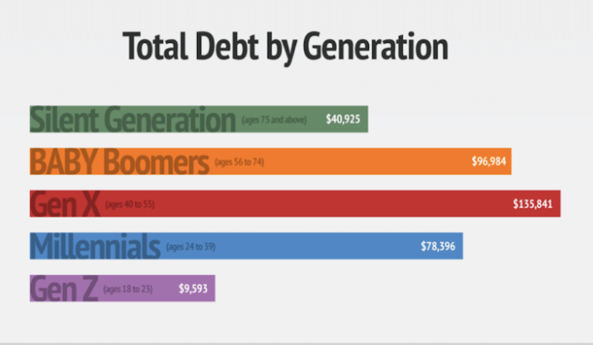
    • Did you know in the US for 50-59-year-olds the average debt is $23,719 1.
  • How Can Budgeting Secure Your Financial Future? Being unsure of where your money is going is a red flag. Budgeting is crucial to track and control spending, ensuring your expenditures align with your values.
    • Did you know the average individual aged between 65 to 74 spends about $55,000 on living expenses annually​2​.
  • How do Savings and Investments Impact Your Retirement Goals? Setting aside money for an emergency fund and future investments is essential. Automating this process by having a portion of your income transferred to savings or investment accounts can help in cultivating this good financial habit.
    • Americans believe they need an average of $1.7 million to retire comfortably, although many won't accumulate enough net worth to retire​3​.
    • As of 2019, only 11% of Baby Boomers managed to save up to $500,000 for their retirement​2​.


Screenshot 2023-11-21 at 3.06.25 PM

What Does Adopting a Frugal Lifestyle Entail?

Frugality is about making informed and restrained financial decisions to save money. A frugal lifestyle encourages avoiding unnecessary expenses and finding value in what you spend.


  • Examples of frugal practices include avoiding spending triggers like malls or online shopping platforms, utilizing cash over credit to prevent overspending, and finding cost-effective alternatives for everyday expenses.


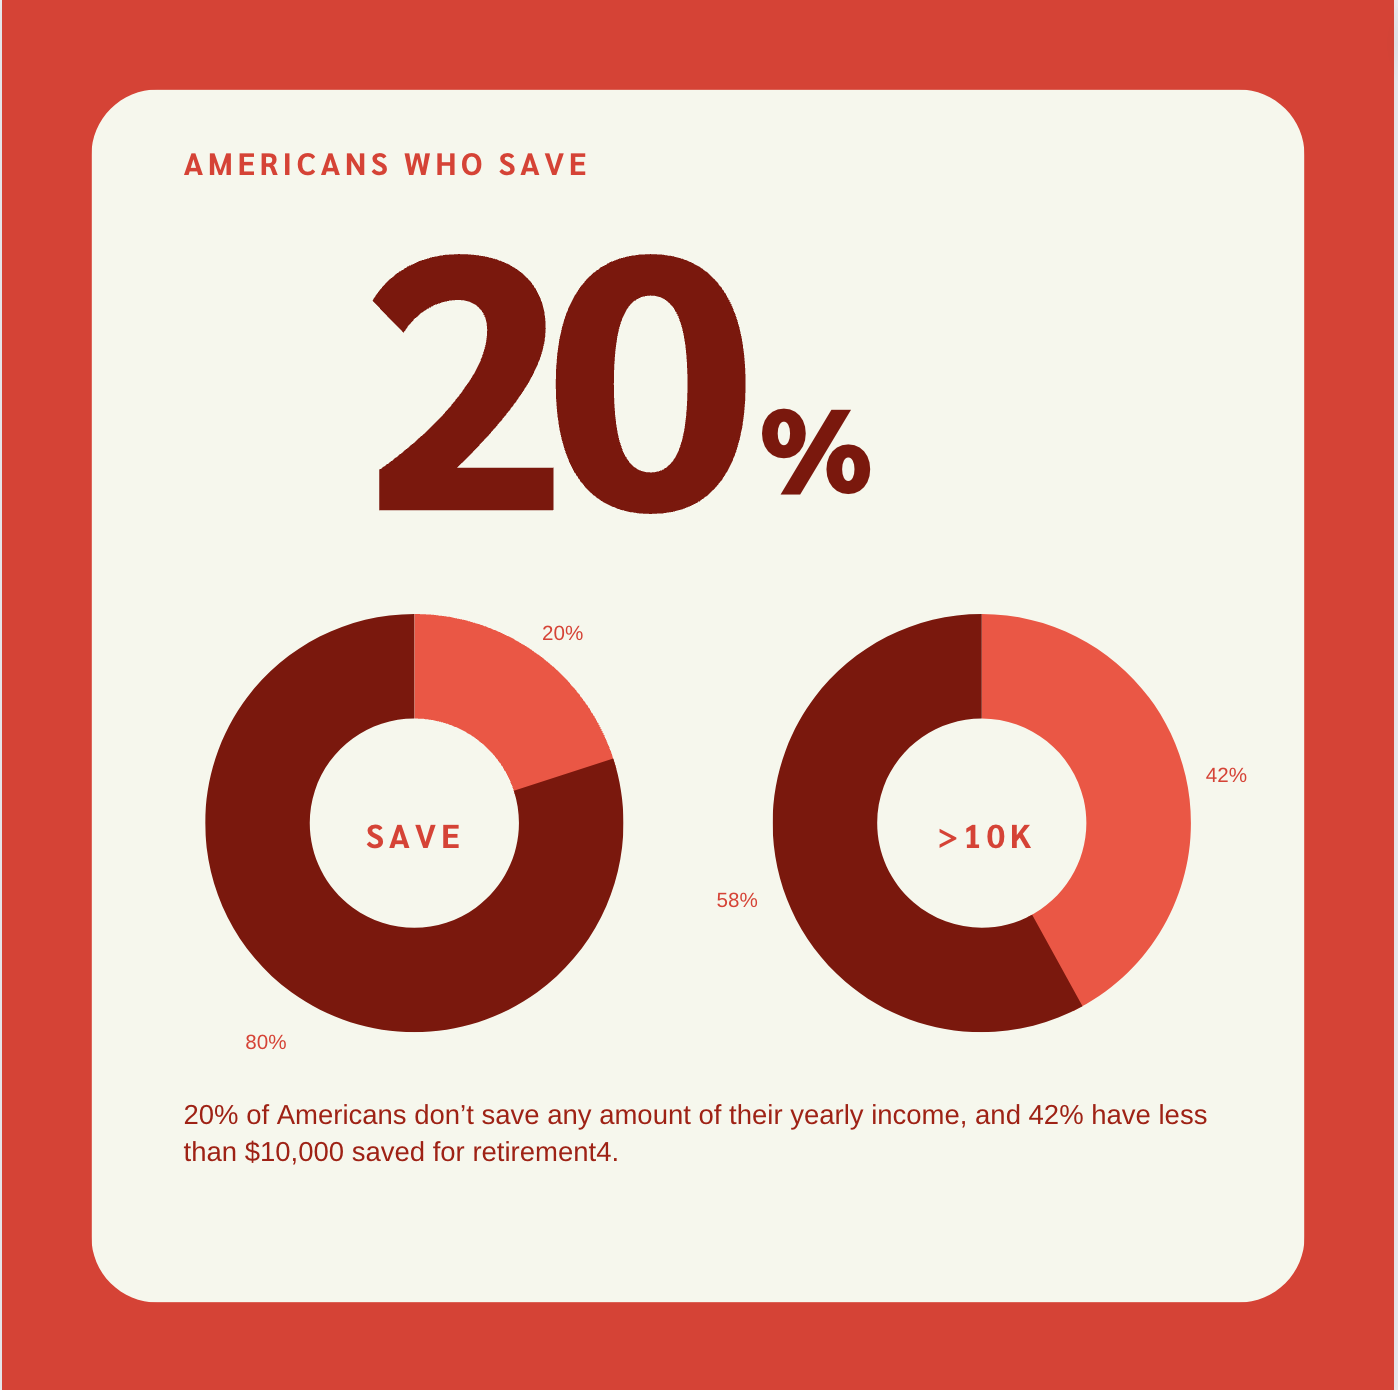
Did you know 20% of Americans don’t save any amount of their yearly income, and 42% have less than $10,000 saved for retirement​4​.


What are the Key Components of Financial Planning for Early Retirement?


  • Emergency Fund: Ensuring you have an emergency fund can help buffer against unforeseen circumstances like a job loss or medical crisis, which might otherwise derail your financial plans.
  • Investment Strategy: Diversifying your investments and aligning them with your retirement goals is imperative for financial growth.
    • 84% of Americans have a higher income than their parents did at the same age, indicating potential for savings and investment if managed wisely​4​.
  • Tax Planning: Efficient tax planning can help in preserving your wealth and ensuring more of your money is working for you rather than going towards taxes.
  • Healthcare Planning: As healthcare costs can be exorbitant, planning for these expenses is crucial to avoid financial strain in later years.
    • Healthcare can be a significant part of living expenses, as seen in the $55,000 annual spending for individuals aged 65-74​5​.


Which Tools and Resources Can Aid Your Financial Planning Journey?


There are myriad tools and resources available to aid in your financial planning journey. Budgeting apps, financial advisors, and online courses are excellent resources. Trilogy Financial, for instance, offers a Decision Coach program designed to provide additional accountability and coaching to individuals seeking financial guidance.

  • 37% of workers aged 25 and older, and 19% of retirees, report not knowing where to go for financial or retirement planning advice​5​.

Easily Meet with a Certified Financial Planner.


image3-1
 

How Have Others Achieved Financial Independence and Early Retirement?


The quest for early retirement often begins with a thorough re-evaluation of one's financial plan, identifying areas of improvement, and capitalizing on unforeseen savings opportunities. The year 2020 saw many Americans saving more, with an average of 10% more money saved compared to 2019, mainly due to lifestyle changes induced by the pandemic. Some redirected these savings towards home improvements, while others saw it as a stepping stone towards drafting a solid financial plan aimed at debt reduction, college planning, or accelerating the journey to financial independence.


Various individuals and communities dedicated to frugal living and meticulous financial planning have emerged over the years, showcasing diverse pathways to early retirement. Here are a few noteworthy examples:


  • Juan's Early Retirement Ambition: Juan, an aspiring early retiree, aimed to bid farewell to his federal job by 2031 at the age of 43. His strategy revolved around living off savings, investments, and dividends post-retirement to enjoy more time with family and delve into philanthropic ventures. Though new to the Financial Independence, Retire Early (FIRE) movement, Juan's no debt and $85,000 asset accumulation puts him in a favorable position towards achieving his goal​1​.
    • The FIRE Movement: The Financial Independence, Retire Early (FIRE) community exemplifies the synergy between frugal living and early retirement. Members of this movement, like Juan, embody a lifestyle of extreme savings and frugality, aiming to retire much earlier than the conventional age​2​.
  • Young Adults Eyeing Early Retirement: The allure of early retirement isn't confined to older age groups. One in four individuals between 18 to 34 years old has set early retirement as their significant financial milestone, driven by the principles of frugal living and meticulous financial planning​3​.
  • A 5-Year Transition Plan: A couple outlines their 5-year plan towards financial independence, with one partner continuing full-time work for an additional 3-4 years, demonstrating a balanced approach to achieving early retirement while maintaining a comfortable lifestyle​4​.
  • Frugal Living as a Fast Track to Early Retirement: The narrative of saving 75% of income, a hallmark of frugal living, expedites the journey towards early retirement, allowing individuals to accumulate substantial savings, invest wisely, and achieve financial independence sooner​5​.


These cases highlight the transformative impact of frugal living and prudent financial planning to achieve early retirement dreams. They speak to the importance of continuous financial plan evaluation, adapting to changing circumstances, and leveraging savings opportunities to expedite the journey to financial independence and early retirement.


Conclusion:

The road to early retirement is laden with challenges, primarily stemming from our own financial bad habits. However, if we create a financial plan, adopt a frugal lifestyle, and leverage available resources, overcoming these challenges and retiring early is an achievable goal.


Get Started on Your Financial Life Plan Today