Life Insurance: It’s Not Just For Your Parents

By
July 23, 2019
Share on:

Like many in my generation, I prefer to subconsciously minimize the odds that I’ll become ill and ignore the reality that I’ll eventually pass. Unfortunately, the harsh reality is that illness and death are inevitable. Enter another subject we tend to ignore: Life Insurance. For many Americans – particularly young and/or single adults, life insurance is nothing more than a plot point in a Hollywood movie or true crime drama: the money collected by remaining relatives after someone has passed. However, life insurance, like health insurance, is just something you need to have. It can provide financial security for your loved ones, cover end of life expenses, and can even provide tax free income.

There are two different types of life insurance: temporary and permanent. The most common form of temporary insurance is Term insurance. Term typically lasts for a specified “term” of years, hence its name. Permanent – on the other hand – stays with you for your entire life, provided you continue to pay the premium, or have developed an account value large enough you no longer have to pay in. There are a wide variety of insurance policies available under the permanent life insurance umbrella, such as: whole life, universal life, variable universal life, and indexed universal life.

To put in another way, Term insurance can be thought of as renting insurance. You pay a monthly premium for the coverage but once the specified term of time is up that coverage goes away. The term can vary from 5 years up to 30 years. With some companies you can continue the policy, but you will have to pay premiums that are a multiple of what you had been paying during the “term” of the contract. It is used to provide protection for liabilities that will disappear after a certain time period ex: raising children, your mortgage, or income replacement. In your 20s-50s you have more people depending on you; therefore, if something were to happen to you (e.g. illness, death) you need an insurance policy that will take care of the people you support. If you pass away, you need enough coverage to pay off any existing debt, provide income replacement, and cover any other miscellaneous expenses associated with supporting your family. This coverage makes a difficult time a little bit easier by reducing the financial burden and allowing loved ones time to grieve without worrying about impending bills. Term insurance is perfect for this type of coverage as it has the lowest premiums and can be structured to disappear once certain liabilities disappear (e.g. mortgage is paid off, kids are out of the house, and your income is no longer critical to the security of your family).

Permanent Insurance, on the other hand, can be framed as owning the insurance coverage. As with term insurance, you pay a monthly premium; however, the coverage stays with you for the rest of your life, not just a specified term of time. Once your family is out of the house and your liabilities are decreased you still want to maintain some level of insurance coverage to cover end of life expenses and provide for loved ones. Permanent insurance is a great choice to cover these remaining liabilities. The premiums for permanent insurance are higher than those for term insurance because, unlike term – where the insurance company may not ever have to pay out the policy- permanent insurance means a guaranteed payout – assuming you’ve paid the premium. At some point the insurance company will have to pay. Additionally, part of these monthly premiums are placed into a cash value account which, depending on the type of policy, earns a fixed or variable rate of return and can provide tax free income. This income can be used to fund an early retirement as it can be accessed prior to age 59 ½ – the age required to legally withdraw from retirement plans without incurring penalties.

But what if you want to access the death benefit in an insurance policy without having to die – sound too good to be true? In fact, some insurance policies allow you to access death benefits before actual death! These policies feature Accelerated Benefit Riders (ABRs) which allow you to accelerate (or, in other words, use) the death benefit while still alive to cover certain terminal, chronic, or critical illnesses. Unlike health insurance, which only reimburses medical expenses, ABRs provide tax free money for you to use as you wish, assuming you have an ABR event. You can use this money for experimental treatments that health insurance will not cover or use it to travel the world. There are no restrictions on how the money is spent.

Now you know about life insurance and the many different options and benefits available to you – consider working with a financial planner to discuss the right life insurance policy for your needs.

If you have questions about insurance or any other aspect of your financial life please do not hesitate to reach out to me at zach.swaffer@trilogyfs.com

This article contains only general descriptions and is not a solicitation to sell any insurance product or security, nor is it intended as any financial or tax advice. For information about specific insurance needs or situations, contact your insurance agent. This article is intended to assist in educating you about insurance generally and not to provide personal service. Guarantees are based on the claims paying ability of the issuing company.

The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.
You may also like:

By Trilogy Financial
February 20, 2024

Have you ever envisioned a life of Financial Freedom and Leisure?

Have you ever envisioned a life where the chains of daily grind are broken well before the conventional retirement age, paving the way for a life of financial freedom and leisure? Embracing financial discipline and frugality can pave the way to a comfortable early retirement, answering the pressing question: Can meticulous financial planning and a frugal lifestyle significantly hasten your journey to early retirement?


What Makes Financial Planning Crucial?


Financial planning goes beyond merely saving a portion of your income; it's about understanding and rectifying financial bad habits that may impede your journey towards financial stability. Everyday financial misbehaviors such as impulsive spending, credit card debt, and the lack of a structured financial plan for emergencies often go unnoticed but have a long-term detrimental impact on financial health. Addressing these personal finance habits is the first step in financial planning.


  • Why is Debt Management Essential? A key aspect of financial planning involves managing or eliminating debt, which can otherwise consume a significant portion of your income in the form of interest payments.
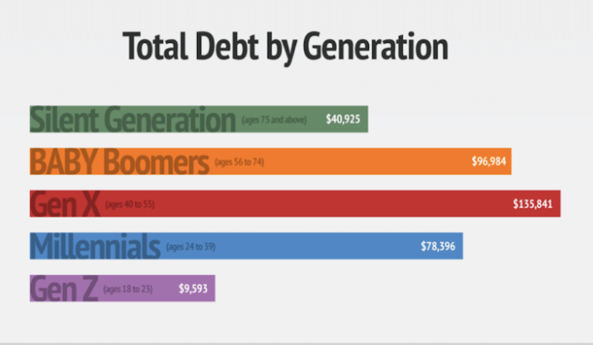
    • Did you know in the US for 50-59-year-olds the average debt is $23,719 1.
  • How Can Budgeting Secure Your Financial Future? Being unsure of where your money is going is a red flag. Budgeting is crucial to track and control spending, ensuring your expenditures align with your values.
    • Did you know the average individual aged between 65 to 74 spends about $55,000 on living expenses annually​2​.
  • How do Savings and Investments Impact Your Retirement Goals? Setting aside money for an emergency fund and future investments is essential. Automating this process by having a portion of your income transferred to savings or investment accounts can help in cultivating this good financial habit.
    • Americans believe they need an average of $1.7 million to retire comfortably, although many won't accumulate enough net worth to retire​3​.
    • As of 2019, only 11% of Baby Boomers managed to save up to $500,000 for their retirement​2​.


Screenshot 2023-11-21 at 3.06.25 PM

What Does Adopting a Frugal Lifestyle Entail?

Frugality is about making informed and restrained financial decisions to save money. A frugal lifestyle encourages avoiding unnecessary expenses and finding value in what you spend.


  • Examples of frugal practices include avoiding spending triggers like malls or online shopping platforms, utilizing cash over credit to prevent overspending, and finding cost-effective alternatives for everyday expenses.


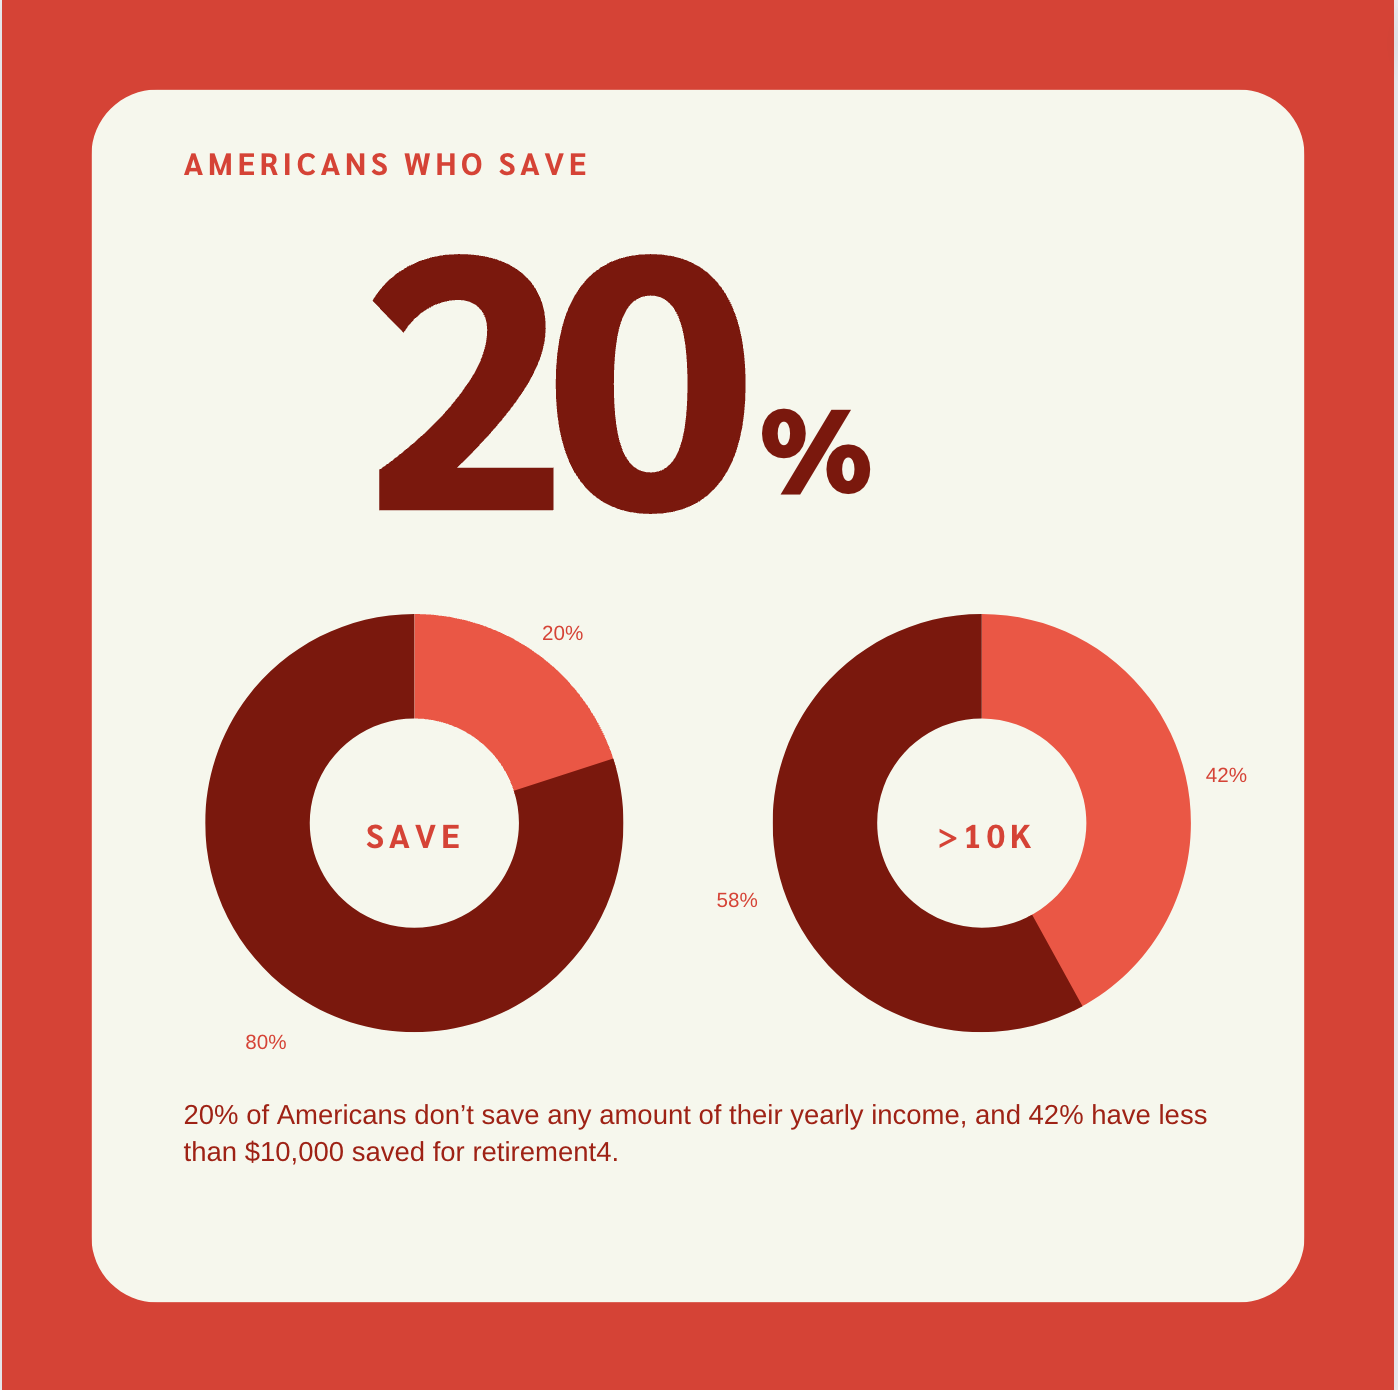
Did you know 20% of Americans don’t save any amount of their yearly income, and 42% have less than $10,000 saved for retirement​4​.


What are the Key Components of Financial Planning for Early Retirement?


  • Emergency Fund: Ensuring you have an emergency fund can help buffer against unforeseen circumstances like a job loss or medical crisis, which might otherwise derail your financial plans.
  • Investment Strategy: Diversifying your investments and aligning them with your retirement goals is imperative for financial growth.
    • 84% of Americans have a higher income than their parents did at the same age, indicating potential for savings and investment if managed wisely​4​.
  • Tax Planning: Efficient tax planning can help in preserving your wealth and ensuring more of your money is working for you rather than going towards taxes.
  • Healthcare Planning: As healthcare costs can be exorbitant, planning for these expenses is crucial to avoid financial strain in later years.
    • Healthcare can be a significant part of living expenses, as seen in the $55,000 annual spending for individuals aged 65-74​5​.


Which Tools and Resources Can Aid Your Financial Planning Journey?


There are myriad tools and resources available to aid in your financial planning journey. Budgeting apps, financial advisors, and online courses are excellent resources. Trilogy Financial, for instance, offers a Decision Coach program designed to provide additional accountability and coaching to individuals seeking financial guidance.

  • 37% of workers aged 25 and older, and 19% of retirees, report not knowing where to go for financial or retirement planning advice​5​.

Easily Meet with a Certified Financial Planner.


image3-1
 

How Have Others Achieved Financial Independence and Early Retirement?


The quest for early retirement often begins with a thorough re-evaluation of one's financial plan, identifying areas of improvement, and capitalizing on unforeseen savings opportunities. The year 2020 saw many Americans saving more, with an average of 10% more money saved compared to 2019, mainly due to lifestyle changes induced by the pandemic. Some redirected these savings towards home improvements, while others saw it as a stepping stone towards drafting a solid financial plan aimed at debt reduction, college planning, or accelerating the journey to financial independence.


Various individuals and communities dedicated to frugal living and meticulous financial planning have emerged over the years, showcasing diverse pathways to early retirement. Here are a few noteworthy examples:


  • Juan's Early Retirement Ambition: Juan, an aspiring early retiree, aimed to bid farewell to his federal job by 2031 at the age of 43. His strategy revolved around living off savings, investments, and dividends post-retirement to enjoy more time with family and delve into philanthropic ventures. Though new to the Financial Independence, Retire Early (FIRE) movement, Juan's no debt and $85,000 asset accumulation puts him in a favorable position towards achieving his goal​1​.
    • The FIRE Movement: The Financial Independence, Retire Early (FIRE) community exemplifies the synergy between frugal living and early retirement. Members of this movement, like Juan, embody a lifestyle of extreme savings and frugality, aiming to retire much earlier than the conventional age​2​.
  • Young Adults Eyeing Early Retirement: The allure of early retirement isn't confined to older age groups. One in four individuals between 18 to 34 years old has set early retirement as their significant financial milestone, driven by the principles of frugal living and meticulous financial planning​3​.
  • A 5-Year Transition Plan: A couple outlines their 5-year plan towards financial independence, with one partner continuing full-time work for an additional 3-4 years, demonstrating a balanced approach to achieving early retirement while maintaining a comfortable lifestyle​4​.
  • Frugal Living as a Fast Track to Early Retirement: The narrative of saving 75% of income, a hallmark of frugal living, expedites the journey towards early retirement, allowing individuals to accumulate substantial savings, invest wisely, and achieve financial independence sooner​5​.


These cases highlight the transformative impact of frugal living and prudent financial planning to achieve early retirement dreams. They speak to the importance of continuous financial plan evaluation, adapting to changing circumstances, and leveraging savings opportunities to expedite the journey to financial independence and early retirement.


Conclusion:

The road to early retirement is laden with challenges, primarily stemming from our own financial bad habits. However, if we create a financial plan, adopt a frugal lifestyle, and leverage available resources, overcoming these challenges and retiring early is an achievable goal.


By Trilogy Financial
November 2, 2017

The day you become a parent is a day of overwhelming emotions. You may experience joy at the sight of your precious child, relief that he or she made it out of the womb, and for many of you, fear and anxiety because you somehow have to turn that seven-pound baby into an independent, responsible, and successful adult.

As parents, there are so many things we have to teach our children, beginning with the basics of how to eat and share toys to more complicated lessons such as making decisions and getting along with others. As a society, we are excelling in some areas of parenting, but falling behind in others. In a recent National Financial Capabilities Study, only 24 percent of Millennials (age 23-35) were able to answer the first three financial literacy questions correctly, and a mere 8 percent answered them all correctly.[1]

Most parents agree that we need to do a better job teaching our kids about money. Last year, T Rowe Price reported that 80 percent of parents didn’t think schools were doing enough to teach kids about financial matters.[2]However, parents cannot abdicate all responsibility to the schools. Raising children and teaching them to navigate the world is first and foremost a parent’s responsibility.

Set A Good Financial Example

The first step in teaching your kids about finances is modeling what you want them to learn. Few parents would disagree with this concept. The same T Rowe Price study mentioned above found that 69 percent of parents are very/extremely concerned about setting a good financial example for their kids. The vast majority, eight out of ten, feel that they are setting a good financial example, but two-thirds also admit to doing things that wouldn’t qualify as setting a good example.

An enormous 40 percent admitted that when it comes to talking to their kids about finances, it’s “Do as I say, not as I do.” Anyone who has raised kids knows that isn’t enough. My clients tell me they are very concerned about setting a good example for their children. The first step in teaching your kids about money is simple: Show them.

Talk About Finances

Sometimes a silent model isn’t quite enough, and some areas of personal finance aren’t very visible. That is why it is imperative to talk to your kids about finances. But talking about money may be a long-standing cultural taboo. Often this reluctance to discuss financial matters spills over into the home as well.

Forty-nine percent of the parents in the T Rowe Price study said they rarely or never discuss family finances with their children. Eighteen percent admitted to being very/extremely reluctant to discuss financial matters with their kids and 72 percent of parents experience at least some reluctance to having such a discussion. But how are kids going to learn about money if you avoid talking to them about it?  Some topics require more in-depth discussion and openness and finances are one of them.

Get Your Kids Involved

If you want financial understanding to actually sink in, you need to get your kids involved. Learning theory and research have consistently shown that the more active a learning experience is, the greater the learning gains and retention.[3] Most people have to do something to truly learn it.

How does this work with kids? Here are some ways I’ve put this into practice with my daughter: Even though she is young, I have taught her the difference between a penny, nickel, dime and quarter. Beyond just teaching the values of the coins, I then show her how to earn money by completing basic, age-appropriate chores such as making her bed and folding her clothes. As her coins start adding up, she has the opportunity to buy a toy or to save her money and earn interest (a penny for every dollar). Just as any adult, she loves the idea of making money for no extra work, so she often chooses the savings option!

At this point, I take a step back and let my daughter make her own financial decisions (and sometimes mistakes) so that she can learn from them. She and I have different values and I’ve learned that I need to let her be independent and respect her choices. On one occasion, she decided to impulsively purchase a My Little Pony beanie baby that I thought would be a waste of money. Rather than refusing to buy the toy for her, I took a step back and allowed her to buy it with her own money. Sometimes I am surprised in the process, as she still plays with this toy three months later!

Imparting financial wisdom to your kids is a challenging process that takes years. So, if you don’t feel like you’re doing an adequate job of teaching your kids about money, you’re not alone. Even if you are doing a good job, you probably agree with the 77 percent of the T Rowe Price survey parents who said that they wished there were more resources available to help them teach their kids about financial matters.

I believe that every child can learn critical financial lessons at a young age that will set them up for future success. I want to provide you with the tools to help you on this journey. To set up a meeting, call my office at (949) 221-8105 x 2128, or email me at mike.loo@trilogyfs.com.

[1] http://gflec.org/wp-content/uploads/2015/01/a738b9_b453bb8368e248f1bc546bb257ad0d2e.pdf

[2] https://corporate.troweprice.com/Money-Confident-Kids/images/emk/2015-PKM-Report-2015-FINAL.pdf

[3] http://www.joe.org/joe/1994august/a6.php

Get Started on Your Financial Life Plan Today