The FIRE Movement – Is It For You?

By Trilogy Financial
October 30, 2019
Share on:

FIRE, an acronym for “Financial Independence, Retire Early” is trending as a new financial lifestyle.  In a nutshell, FIRE promotes extreme savings in your 20s, 30s, and 40s, with the goal of being able to live off passive income from the accumulated nest egg much earlier than typical retirement age.  Some proponents suggest saving 70% of your income until you have collected 25x your annual salary, cutting your working years in half.  Extreme saving is not a new idea, but the phrase has taken off in the last couple of years, creating a cult following online.

Putting aside additional savings to fund a “work optional” lifestyle is a fantastic idea in theory, but most Americans would find it quite difficult to only live on 30% of their income without making DRASTIC changes.  If you are willing to downsize, live with roommates in a cheaper part of town, eat beans and rice, drive an old car/take the bus, and limit purchases, you could be successful at FIRE.  However, this level of deprivation may cause unintended sacrifices that impact your social life and happiness.

Our take on FIRE is to find your happy medium.  For example, you absolutely should increase your savings rate incrementally every year if you can afford to do so, but initially choose an amount that’s attainable.  To help you get started, these are the questions we encourage clients to consider:

1) What is your current cash flow?

Do you have a firm grasp on how much you spend on monthly groceries?  Going out to eat? Gifts at the holidays for friends and family?  The key here is to consider all expenses, not just big-ticket fixed items like your car payment or mortgage.  Once you have an idea of how much you are spending compared to household income, you can then evaluate your current savings rate.

2) Where can you cut back to increase your savings rate?

Can you meal prep on Sundays to avoid going out for lunch during the week?  Can you stay in to watch a movie instead of going to a theater for date night?  Are you willing to have a “no-spend” week?  Some people use tracking software (our firm provides EMoney to our clients) to help set up electronic budgets to alert you when you are close to going over set categories of spending. Alternatively, can you bring in additional income via a side hustle?  Can you work additional hours at work to qualify for overtime pay?  Make an honest assessment to determine where you could potentially improve your cash flow on a monthly basis.

3) Are you debt-free, or leveraging debt appropriately?

A mortgage with a low-interest rate is an appropriate means of financing a lifestyle you want, while potentially building equity via real estate.  If you still have student loans or credit card debt, though, your increased cash flow should go towards paying this off ASAP. Just make sure you have 3-6 months of living expenses built up in an easily accessible emergency savings account as well.

4) Outside of your emergency savings, are your accounts keeping pace with inflation?

Historically, inflation rates average around 3% annually.  This means that your purchasing power decreases, as the cost of goods increases over time. Remember when you could buy a Coke bottle out of a vending machine for a dollar? Your parents or grandparents may even recall purchasing a soda for a quarter!  That’s inflation at work. If you’re planning to retire early, this means you need to account for inflation over several decades. The best way to maintain your purchasing power is by investing excess savings in the stock and bond markets and taking advantage of compounding interest over time. A Financial Advisor can determine the best investment strategy for you.

5) Are your investments in a diversified portfolio in line with your risk tolerance?

Trying to time the market to buy and sell holdings is incredibly difficult to do.  Diversification via broader index funds and investing consistently (to take advantage of pullbacks) has proven to be a more successful investment plan for most Americans.  The concern with the FIRE movement is knowing how risky you can or should be with your asset allocation depending on your time horizon to retirement.  For example, if you are closer to reaching your retirement goal, you don’t want 100% of your assets invested in the stock market.   A comprehensive financial planner can help determine how much risk you should be taking on by looking at your finances holistically, and ensuring portfolios are rebalanced regularly according to your needs.

The road to early retirement is still a long one, so you’ll need to regularly evaluate your progress, reassess as needed, and don’t forget to acknowledge small victories!

Our advice is to push yourself to save more, without going to the extremes of the FIRE lifestyle.  If you would like additional accountability, Trilogy offers progress checks through our Decision Coach process more frequently than annual reviews.  And if you need a road map to help find your path to success, reach out with any questions here.

The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual. To determine what is appropriate for you, consult a qualified professional.
You may also like:

By
Darcy Borella, CFP®
February 1, 2018

If you're one of the millions of Americans who received, or are expecting to receive, a tax refund, you are probably trying to decide how to spend it. The average refund this year is around $3,000, a nice chunk of change to throw at one of your goals. Rather than impulse buying that new Apple iWatch or splurging at Sephora, make the best use of this windfall by putting it towards improving your financial situation.

Build Up An Emergency Fund

Some very good friends of mine woke up recently to find that their downstairs had flooded from a burst pipe on the second level. They had to rip up their hard wood floors, replace furniture, and even replace some of the walls. Luckily, their bedroom and their child's nursery was spared, but THIS type of unexpected event is exactly why you need an emergency fund. If they didn't have cash readily available in a savings account, they might have been tempted to put charges for repairs and replacements on a high-interest credit card. Depending on your situation, you should ideally have 3-6 months of regular expenses in the bank. Use your tax refund to start, or top off, your rainy day fund.

Pay Off Debt

The power of compounding interest can work in your favor when investing, but it can also cause debt to grow faster than you might think. Credit card companies apply their interest fees to the amount that you owe initially. But every month (and sometimes every DAY!) after that, the compounding interest will apply to the principal, as well as the previous month's interest. If you want to apply the snowball method, apply your refund to the smallest account you can close out. Alternatively, you can use the “Avalanche” method, and put your refund towards the card with the highest interest rate. Paying off the smallest account might feel good, but if you have double digit interest accruing on a card, get that debt paid off as fast as you can. Take the windfall from your refund and put it towards cleaning up your personal balance sheet.

Fund an Individual Retirement Account

IRAs are one of the greatest savings vehicles you can have for retirement. These vehicles allow you to invest in the market outside of any employer-sponsored plans (like a 401K) with tax-free growth (no capital gains!) until retirement. There are two types of IRAs that are available to the general public: Roth IRAs and Traditional IRAs. With a Roth, you contribute post-tax dollars and don't have to pay income taxes on any distributions in retirement. There is, however, a phase-out limit based on income. With a traditional IRA, you do pay income taxes on distributions in retirement. However, contributions made could be tax-deductible for that tax year (contributions made from January 1st of the current year through April 15th of the following year). As of now, individuals can contribute up to $5,500 per year ($6,500 if you’re age 50 or older), or your taxable compensation for the year, if your compensation was less than this dollar limit.

Monetize Other Financial Goals

Planning to take a big family vacation to Disneyland in 5 years? Dreaming of owning a house but need to build up a sizable down payment? Wondering how you are going to pay for your pre-teen's college tuition? If you have any intermediate goals (prior to retirement), consider opening a brokerage account to help your money grow more efficiently. Statistically, the stock market has more up years than down, and historically, has recovered from those down years relatively quickly. If you have time on you side, consider monetizing these goals by participating in the market at a level that is in line with your risk tolerance.

But If You Must, Splurge…A Little

If you just can't help it, take a small percentage of your refund to treat yourself. Whether it's a nice dinner, a manicure, or checking out a movie with your spouse, take a minute to blow off some steam. Keep this amount small though as the path to wealth is paved with good decisions. Start making good habits today to delay gratification and secure a financial safety net in your future.

By Trilogy Financial
February 20, 2024

Have you ever envisioned a life of Financial Freedom and Leisure?

Have you ever envisioned a life where the chains of daily grind are broken well before the conventional retirement age, paving the way for a life of financial freedom and leisure? Embracing financial discipline and frugality can pave the way to a comfortable early retirement, answering the pressing question: Can meticulous financial planning and a frugal lifestyle significantly hasten your journey to early retirement?


What Makes Financial Planning Crucial?


Financial planning goes beyond merely saving a portion of your income; it's about understanding and rectifying financial bad habits that may impede your journey towards financial stability. Everyday financial misbehaviors such as impulsive spending, credit card debt, and the lack of a structured financial plan for emergencies often go unnoticed but have a long-term detrimental impact on financial health. Addressing these personal finance habits is the first step in financial planning.


  • Why is Debt Management Essential? A key aspect of financial planning involves managing or eliminating debt, which can otherwise consume a significant portion of your income in the form of interest payments.
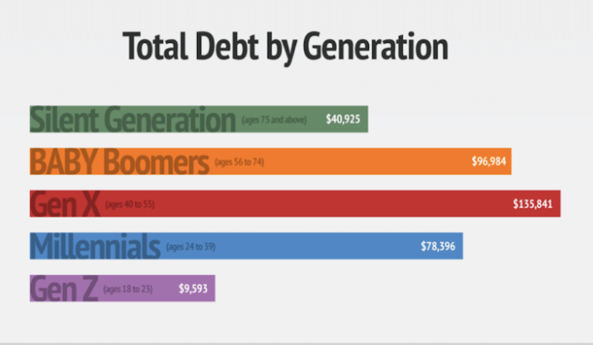
    • Did you know in the US for 50-59-year-olds the average debt is $23,719 1.
  • How Can Budgeting Secure Your Financial Future? Being unsure of where your money is going is a red flag. Budgeting is crucial to track and control spending, ensuring your expenditures align with your values.
    • Did you know the average individual aged between 65 to 74 spends about $55,000 on living expenses annually​2​.
  • How do Savings and Investments Impact Your Retirement Goals? Setting aside money for an emergency fund and future investments is essential. Automating this process by having a portion of your income transferred to savings or investment accounts can help in cultivating this good financial habit.
    • Americans believe they need an average of $1.7 million to retire comfortably, although many won't accumulate enough net worth to retire​3​.
    • As of 2019, only 11% of Baby Boomers managed to save up to $500,000 for their retirement​2​.


Screenshot 2023-11-21 at 3.06.25 PM

What Does Adopting a Frugal Lifestyle Entail?

Frugality is about making informed and restrained financial decisions to save money. A frugal lifestyle encourages avoiding unnecessary expenses and finding value in what you spend.


  • Examples of frugal practices include avoiding spending triggers like malls or online shopping platforms, utilizing cash over credit to prevent overspending, and finding cost-effective alternatives for everyday expenses.


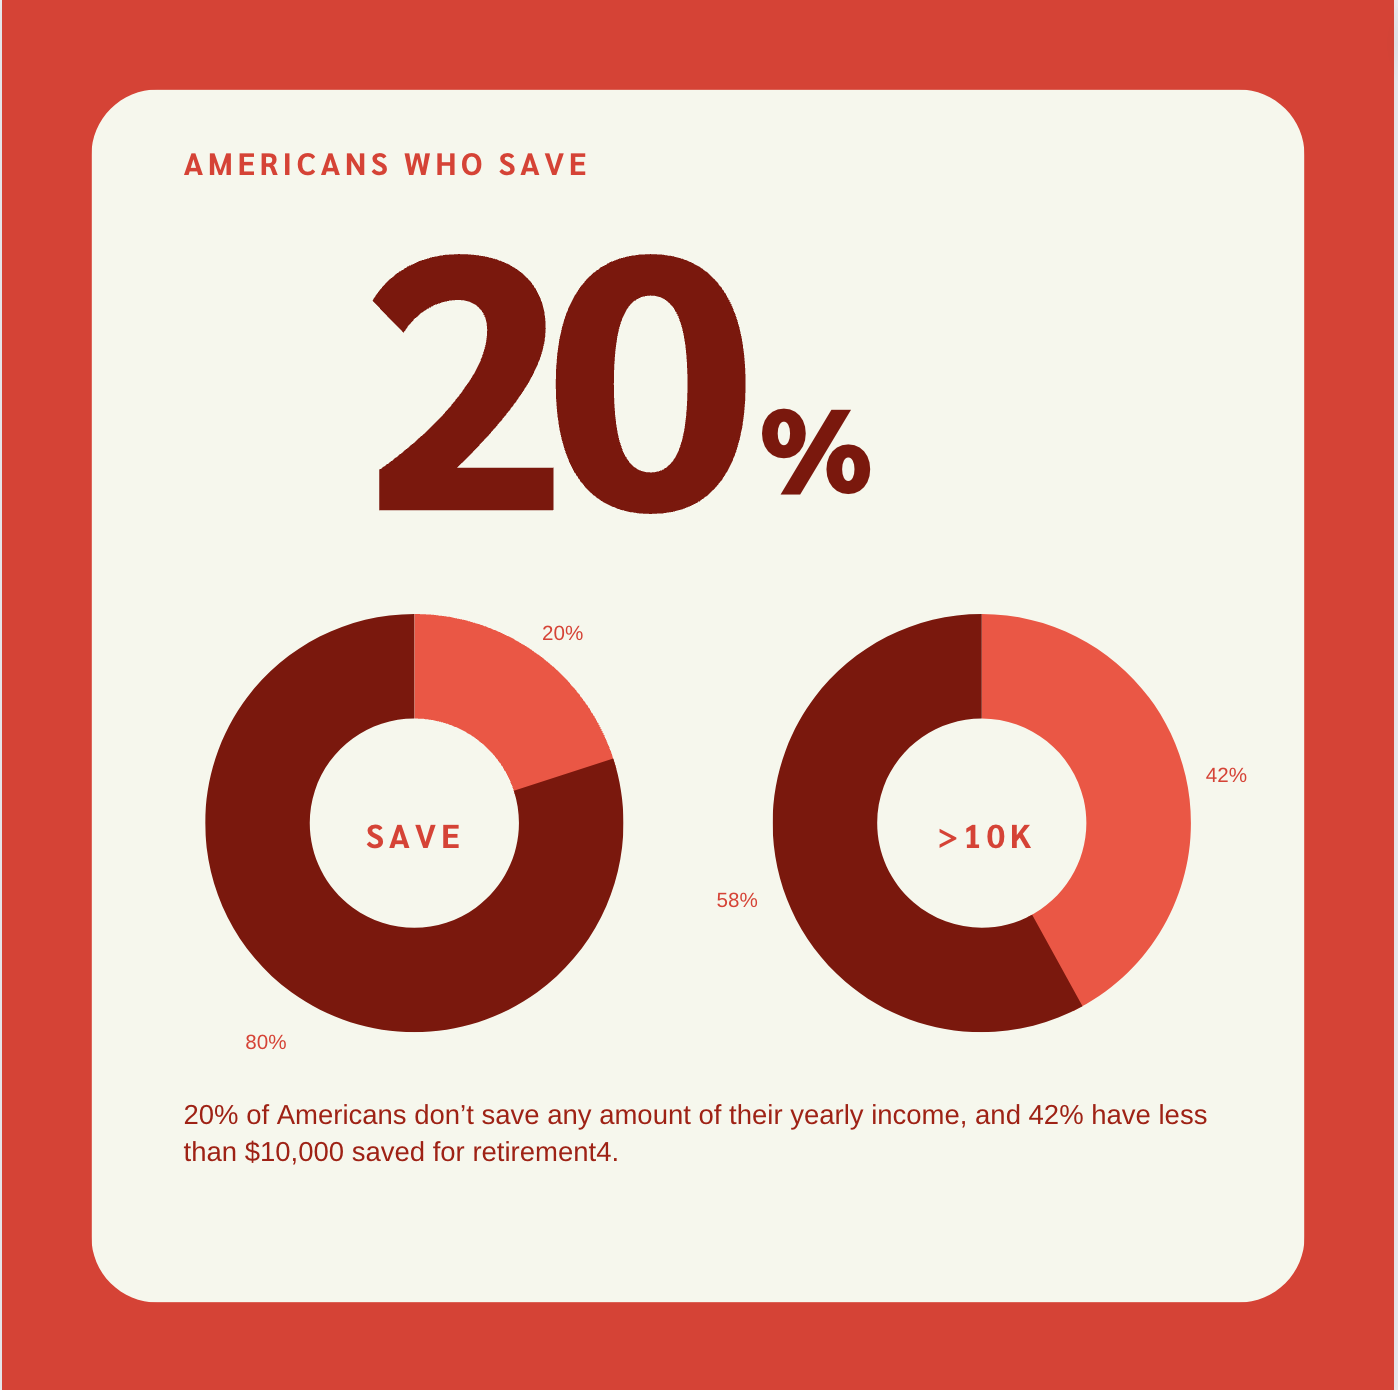
Did you know 20% of Americans don’t save any amount of their yearly income, and 42% have less than $10,000 saved for retirement​4​.


What are the Key Components of Financial Planning for Early Retirement?


  • Emergency Fund: Ensuring you have an emergency fund can help buffer against unforeseen circumstances like a job loss or medical crisis, which might otherwise derail your financial plans.
  • Investment Strategy: Diversifying your investments and aligning them with your retirement goals is imperative for financial growth.
    • 84% of Americans have a higher income than their parents did at the same age, indicating potential for savings and investment if managed wisely​4​.
  • Tax Planning: Efficient tax planning can help in preserving your wealth and ensuring more of your money is working for you rather than going towards taxes.
  • Healthcare Planning: As healthcare costs can be exorbitant, planning for these expenses is crucial to avoid financial strain in later years.
    • Healthcare can be a significant part of living expenses, as seen in the $55,000 annual spending for individuals aged 65-74​5​.


Which Tools and Resources Can Aid Your Financial Planning Journey?


There are myriad tools and resources available to aid in your financial planning journey. Budgeting apps, financial advisors, and online courses are excellent resources. Trilogy Financial, for instance, offers a Decision Coach program designed to provide additional accountability and coaching to individuals seeking financial guidance.

  • 37% of workers aged 25 and older, and 19% of retirees, report not knowing where to go for financial or retirement planning advice​5​.

Easily Meet with a Certified Financial Planner.


image3-1
 

How Have Others Achieved Financial Independence and Early Retirement?


The quest for early retirement often begins with a thorough re-evaluation of one's financial plan, identifying areas of improvement, and capitalizing on unforeseen savings opportunities. The year 2020 saw many Americans saving more, with an average of 10% more money saved compared to 2019, mainly due to lifestyle changes induced by the pandemic. Some redirected these savings towards home improvements, while others saw it as a stepping stone towards drafting a solid financial plan aimed at debt reduction, college planning, or accelerating the journey to financial independence.


Various individuals and communities dedicated to frugal living and meticulous financial planning have emerged over the years, showcasing diverse pathways to early retirement. Here are a few noteworthy examples:


  • Juan's Early Retirement Ambition: Juan, an aspiring early retiree, aimed to bid farewell to his federal job by 2031 at the age of 43. His strategy revolved around living off savings, investments, and dividends post-retirement to enjoy more time with family and delve into philanthropic ventures. Though new to the Financial Independence, Retire Early (FIRE) movement, Juan's no debt and $85,000 asset accumulation puts him in a favorable position towards achieving his goal​1​.
    • The FIRE Movement: The Financial Independence, Retire Early (FIRE) community exemplifies the synergy between frugal living and early retirement. Members of this movement, like Juan, embody a lifestyle of extreme savings and frugality, aiming to retire much earlier than the conventional age​2​.
  • Young Adults Eyeing Early Retirement: The allure of early retirement isn't confined to older age groups. One in four individuals between 18 to 34 years old has set early retirement as their significant financial milestone, driven by the principles of frugal living and meticulous financial planning​3​.
  • A 5-Year Transition Plan: A couple outlines their 5-year plan towards financial independence, with one partner continuing full-time work for an additional 3-4 years, demonstrating a balanced approach to achieving early retirement while maintaining a comfortable lifestyle​4​.
  • Frugal Living as a Fast Track to Early Retirement: The narrative of saving 75% of income, a hallmark of frugal living, expedites the journey towards early retirement, allowing individuals to accumulate substantial savings, invest wisely, and achieve financial independence sooner​5​.


These cases highlight the transformative impact of frugal living and prudent financial planning to achieve early retirement dreams. They speak to the importance of continuous financial plan evaluation, adapting to changing circumstances, and leveraging savings opportunities to expedite the journey to financial independence and early retirement.


Conclusion:

The road to early retirement is laden with challenges, primarily stemming from our own financial bad habits. However, if we create a financial plan, adopt a frugal lifestyle, and leverage available resources, overcoming these challenges and retiring early is an achievable goal.


Get Started on Your Financial Life Plan Today